Real Estate Investing Starts Before You Buy a Property
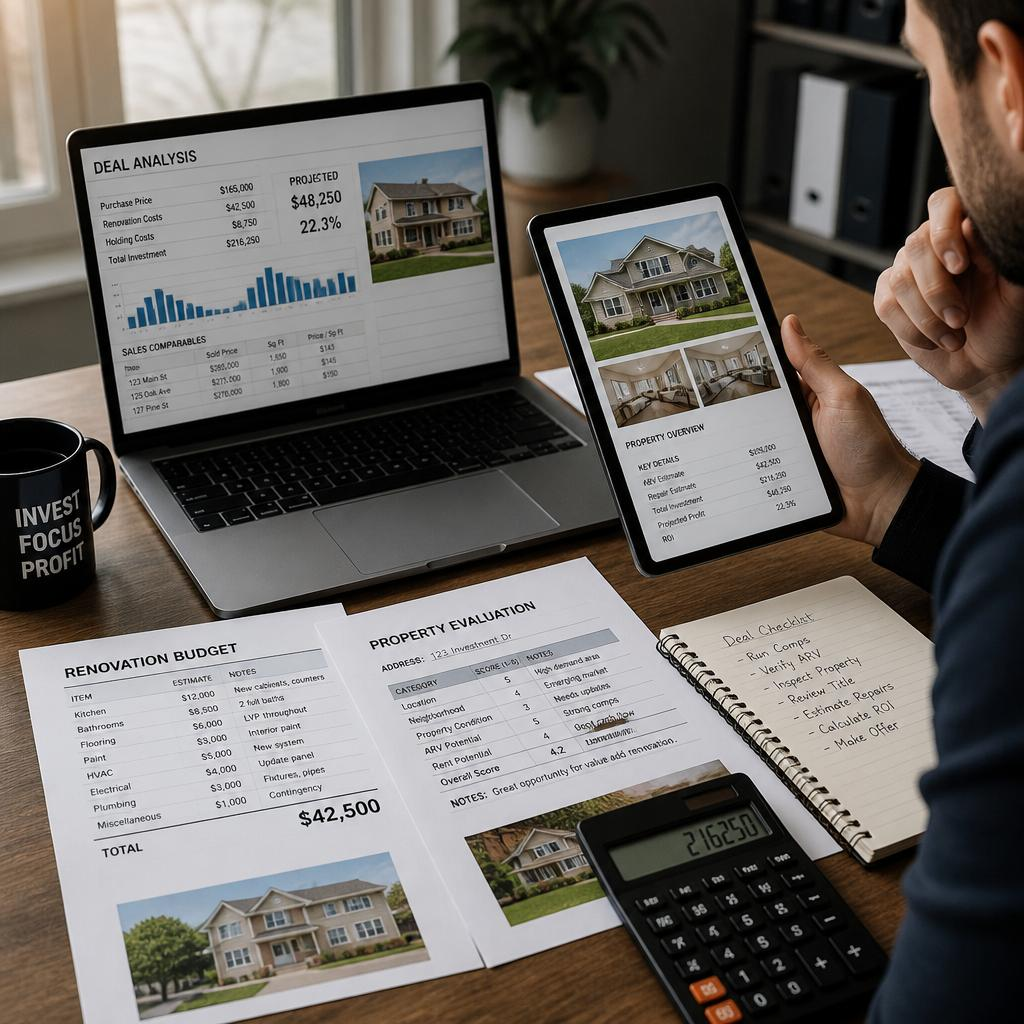
Real estate investing can offer opportunities to generate rental income, build equity, and potentially benefit from long-term property appreciation. But buying an investment property is a financial decision, not simply a matter of finding a house that looks like a good deal.
Before you purchase anything, you need to understand what you want your investment to accomplish, how much money you can commit, which properties fit your strategy, and what you will do if the investment doesn’t perform as expected.
The good news? You don’t need to own five properties to begin thinking like an investor. You need a plan, realistic numbers, and a disciplined process for evaluating opportunities.
This guide walks you through the decisions to make before buying your first investment property.
Step 1: Decide What You Want Real Estate to Do for You
Start with your financial objective. Different investment strategies serve different purposes, and not every strategy is appropriate for every investor.
Ask yourself:
- Am I looking for monthly rental income?
- Do I want to renovate and resell properties?
- Am I trying to build long-term equity?
- Do I want to diversify investments I already own?
- How much time can I devote to the property?
- How much financial risk can I reasonably tolerate?
- When might I need access to the money I invest?
Your answers help narrow the types of properties and investment strategies worth investigating.
For example, an investor who wants a long-term rental may focus on tenant demand, operating expenses, and cash flow. Someone who wants to flip a property may focus on renovation costs, resale value, project duration, and the margin remaining after every expense.
Neither strategy is automatically better. The appropriate choice depends on your circumstances, experience, available capital, and objectives.
Step 2: Choose an Initial Investment Strategy
Buy-and-hold rental properties
You purchase a property and rent it to tenants. The investment may generate income after expenses, and you may build equity over time.
However, rent is not the same as profit. You must account for vacancies, repairs, insurance, property taxes, management, capital expenditures, and financing.
Fix-and-flip properties
You purchase a property, complete improvements, and resell it.
The challenge is accurately estimating the property’s value after repairs, renovation costs, holding expenses, selling costs, and the time required to complete the project.
An attractive difference between the purchase price and projected resale price does not guarantee a profitable flip.
Small multifamily properties
Duplexes, triplexes, and four-unit properties can provide multiple rental units within one investment. They also introduce additional considerations involving maintenance, occupancy, financing, and management.
More units do not automatically mean better returns. The purchase price and operating expenses still need to make sense.
Other strategies
Investors may also consider room rentals, furnished rentals, larger multifamily properties, or other approaches. Each comes with different operational, legal, financing, and market requirements.
Begin by understanding one strategy well rather than attempting to master every strategy at once.
Step 3: Establish Your Actual Investment Budget
Your budget is more than the amount you can put toward a down payment.
Before shopping for properties, estimate the total cash required for acquisition and operation.
Include:
- Down payment or equity contribution.
- Loan origination charges and other financing costs.
- Title, settlement, inspection, appraisal, and other closing costs.
- Immediate repairs and renovations.
- Utilities, insurance, taxes, and other expenses during vacancy or renovation.
- Initial operating expenses.
- A reserve for unexpected repairs, vacancies, and delays.
The appropriate reserve depends on the property, financing, condition, and your financial circumstances. A property requiring a new roof or major mechanical work presents different risks from a recently renovated property.
Avoid committing every available dollar to the purchase. An investment that looks profitable on paper can become a serious financial burden if you cannot fund an unexpected repair or several months without rent.
Step 4: Research the Market Before Choosing a Property
Real estate is local. Two properties with similar prices can have very different investment potential because of location, rental demand, property taxes, condition, and resale prospects.
For investors exploring Northern Illinois, research the specific communities and neighborhoods where you may buy.
Investigate:
- Recent comparable sales.
- Realistic rental rates for similar properties.
- Property taxes and potential reassessment implications.
- Insurance availability and costs.
- Local landlord-tenant requirements.
- Municipal rental licensing or inspection requirements.
- Zoning and permitted uses.
- Flood risks and other property-specific hazards.
- Employment, transportation, amenities, and factors affecting tenant demand.
Do not assume that a property with low taxes today will always have the same tax burden. Do not assume that a rental strategy permitted in one municipality will be permitted in another.
Use current records and verified estimates rather than relying solely on online property estimates or a seller’s projections.
Step 5: Learn to Analyze a Deal
Before making an offer, estimate both income and expenses.
For a rental property, start with realistic expected rent. Then account for vacancy and nonpayment, operating expenses, maintenance, management, and capital reserves.
If you finance the purchase, also examine the mortgage payment and other debt obligations.
A property can show positive cash flow before financing but negative cash flow after debt service. That distinction matters.
For a flip, estimate the after-repair value using relevant comparable sales. Subtract acquisition costs, renovation costs, holding costs, financing costs, resale costs, and an appropriate contingency.
Do not base your decision on the best-case scenario alone. Calculate what happens if rent is lower than expected, repairs cost more, or the project takes longer.
Your objective is not to make the numbers look attractive. It is to discover whether the investment still makes sense under reasonable assumptions.
Step 6: Build Your Professional Team
You do not have to know everything yourself, but you do need access to qualified professionals.
Depending on your strategy, your team may include:
- A real estate broker familiar with investment properties.
- A lender experienced in investment-property financing.
- A qualified property inspector.
- Contractors who can provide written estimates.
- A real estate attorney.
- An accountant or tax professional.
- An insurance professional.
- A property manager, if you will not manage the property yourself.
Ask specific questions about experience, costs, timelines, and potential conflicts of interest.
For example, if a contractor estimates a renovation at $25,000, determine exactly what that estimate includes, whether permits are required, and how unexpected conditions will be handled.
If a lender quotes an attractive rate, compare points, fees, repayment terms, prepayment provisions, and the total cost of borrowing.
Step 7: Find Properties That Match Your Criteria
You can search public listings, work with real estate professionals, attend investor networking events, develop relationships with property owners, and investigate potential off-market opportunities.
Off-market does not necessarily mean below market value. A property may be unavailable to the general public but still be overpriced, unsuitable, or burdened by expensive repairs.
Before you begin searching seriously, write down your preferred property type, location, price range, acceptable condition, financing approach, and purchase timeline.
This is your investor buy box. It helps you focus on relevant opportunities instead of spending hours evaluating properties that never fit your goals.
Step 8: Complete Due Diligence Before Committing
Before closing, investigate the property and verify the information that matters to your investment.
Depending on the transaction, this may include:
- Professional inspections.
- Title and ownership review.
- Permitted use and zoning.
- Rental restrictions and local requirements.
- Repair estimates and contractor availability.
- Property taxes and insurance.
- Lease terms and tenant status.
- Existing liens or other title concerns.
- Financing conditions and closing requirements.
- Actual or supportable rental and resale assumptions.
Do not waive important protections without understanding the risks. If the seller, lender, or another party is applying pressure to move quickly, that is a reason to be especially clear about what remains unverified.
Step 9: Decide How You Will Operate the Property
Buying the property is only the beginning.
For rentals, decide who will handle advertising, tenant screening, lease administration, rent collection, repairs, recordkeeping, and compliance with applicable housing laws.
For flips, establish a project schedule, a system for approving additional work, and a method for tracking actual costs against the budget.
A property that requires more management than you can provide may not be a suitable investment, even if the projected return looks attractive.
Step 10: Make Your First Investment a Learning Process
Your first property does not have to be the biggest property you can afford. It should be an investment whose risks, costs, and operational demands you understand.
Document your assumptions before purchase. After acquisition, compare actual results with your original estimates. Record unexpected expenses, vacancy, repair costs, financing costs, and the time required to manage the property.
That information will help you evaluate future purchases with greater confidence.
First-Time Investor Checklist
Before making an offer, make sure you can answer these questions:
- What is my investment objective?
- Which strategy fits my financial circumstances?
- How much cash can I commit without exhausting my reserves?
- What is my total acquisition budget?
- What are the realistic income and expense assumptions?
- What happens if the property needs more work than expected?
- Have I researched the local market and applicable rules?
- Have I identified the professionals I need?
- Have I completed appropriate due diligence?
- Do I have a plan for managing the property after closing?
If you cannot answer several of these questions yet, that is not a reason to abandon investing. It is a sign of what you need to learn before committing your money.
Ready to Define Your Investment Goals?
Northern Illinois Investor Connection is designed for investors who want to clarify what they are looking to buy and explore potential property opportunities.
Whether you are researching your first rental or expanding an existing portfolio, start by defining your preferred locations, property types, price range, and investment objectives.
Join Northern Illinois Investor Connection for free and share your buying criteria.
This article provides general educational information, not individualized financial, legal, tax, lending, or investment advice. Real estate investments involve risk, and outcomes are not guaranteed. Verify property-specific information and consult qualified professionals before making investment decisions.